A consumer proposal doesn’t end your chances of owning a home. It changes the timeline, the lenders you’ll work with and what your application needs to show, but you can get a mortgage during a consumer proposal and after it’s complete. Many Canadians buy or refinance within a year or two of finishing their proposal.
This guide explains how lenders view a proposal, what’s possible at each stage, the documents you’ll need, and the steps that get you approved sooner and at a lower cost.
Already own a home and worried about your renewal? See will a consumer proposal affect your mortgage renewal.
Table of Contents
ToggleCan You Get a Mortgage After a Consumer Proposal?
Yes. Lenders focus on three things:
- Stability: have you completed the proposal, or are you on track with every payment?
- Re-established credit: do you have new credit accounts paid on time?
- Affordability: can your income support the new payment within lending limits?
Even during a proposal, some lenders will approve a refinance with enough equity, or a purchase with a large down payment. Once the proposal is complete and you’ve rebuilt credit, your options grow quickly.
How a Consumer Proposal Affects Your Credit
When you file, the accounts included in the proposal are reported as R7, the second-lowest rating. That’s why most banks decline during a proposal and for a while after it ends.
The proposal itself generally stays on your credit file until 3 years after you complete it, or 6 years from the date you filed, whichever comes first. Most people’s scores drop significantly when they file, then recover steadily as they use new credit responsibly.
The damage is real, but it’s temporary, and every month of clean payments moves you closer to better lenders.
How Lenders See a Consumer Proposal
| Lender | When they’ll consider you | What they focus on |
|---|---|---|
| Private lenders | During the proposal and right after | Equity or down payment, and your exit plan |
| B lenders (alternative) | Some during, most within the first year after completion | Income, at least 20% down or equity, re-established credit |
| A lenders (banks, insured mortgages) | Usually about 2 years after completion | Rebuilt credit, stable income, standard debt ratios |
Many borrowers follow a staged plan: a private or B lender now, then a move to a bank once their credit has recovered. Planning that path from the start keeps your total cost down.
The Consumer Proposal Mortgage Timeline
During an Active Proposal
Approvals are possible, mainly through private lenders and select B lenders, based on your equity or down payment and your ability to make the new payment. Your credit score matters less at this stage, because the R7 accounts dominate your file.
Private mortgages are usually 12 or 24 month bridges. Estimated private rates are 6.99% to 10.99% for a first mortgage and 7.99% to 14.99% for a second mortgage, plus a lender fee and a broker fee, each disclosed separately. Rates are estimates only and subject to change.
Common myth: you can’t get a mortgage at all during a proposal. Private lenders approve these files regularly when there’s enough equity.
Using Home Equity to Pay Off Your Proposal Early
If you own your home, a refinance or a second mortgage can pay the rest of your proposal in one payment. You can usually pay a consumer proposal off early without penalty. Paying early gets you your Certificate of Full Performance sooner, and that starts your recovery clock.
What to weigh: the cost of the private loan against how much sooner you’ll qualify for better rates. A broker can map out both paths.
The First Year After Completion
Once you receive your Certificate of Full Performance, B lenders become much more comfortable with your file, especially if you have one or two new credit accounts paid on time. Expect rates above bank rates, with at least 20% down or 20% equity.
Two Years After Completion and Beyond
By about two years after completion, with rebuilt credit and stable income, banks and insured mortgages generally become available again. That’s when lower rates, and minimum down payments with mortgage insurance, come back within reach.
Important to note: the two-year mark opens the door, but it isn’t an automatic approval. Your income, credit, down payment and the property still need to fit the lender’s rules.
Can You Buy a House With a Consumer Proposal?
Yes, but buying is harder than refinancing, because you don’t yet have equity to lean on.
- During the proposal: usually private or select B lenders, with a large down payment, often 20% to 35%.
- In the first year after completion: B lenders, typically with at least 20% down.
- About two years after completion: banks and insured mortgages, where smaller down payments become possible.
A larger down payment opens more lenders and better rates at every stage. See our home buyer mortgage options.
Your Mortgage Approval Toolkit: Documents Lenders Want
Proposal documents
- Active proposal: a copy of the filed proposal, your trustee’s latest statement, and proof of payments made
- Completed proposal: your Certificate of Full Performance, the most important document in a post-proposal application. Ask your trustee for it as soon as you finish.
Income
- Salaried: two recent pay stubs and an employment letter
- Self-employed: two years of T1 Generals and Notices of Assessment, plus business bank statements (see our self employed mortgage options)
Other
- Credit reports from Equifax and TransUnion (your broker will pull these)
- Down payment: 90 days of bank history showing where the money came from, or a gift letter
- Purchase: the listing and the signed agreement
- Refinance: your mortgage statement, property tax bill and an appraisal
7 Ways to Get Approved Sooner After a Consumer Proposal
1. Rebuild Credit Right Away
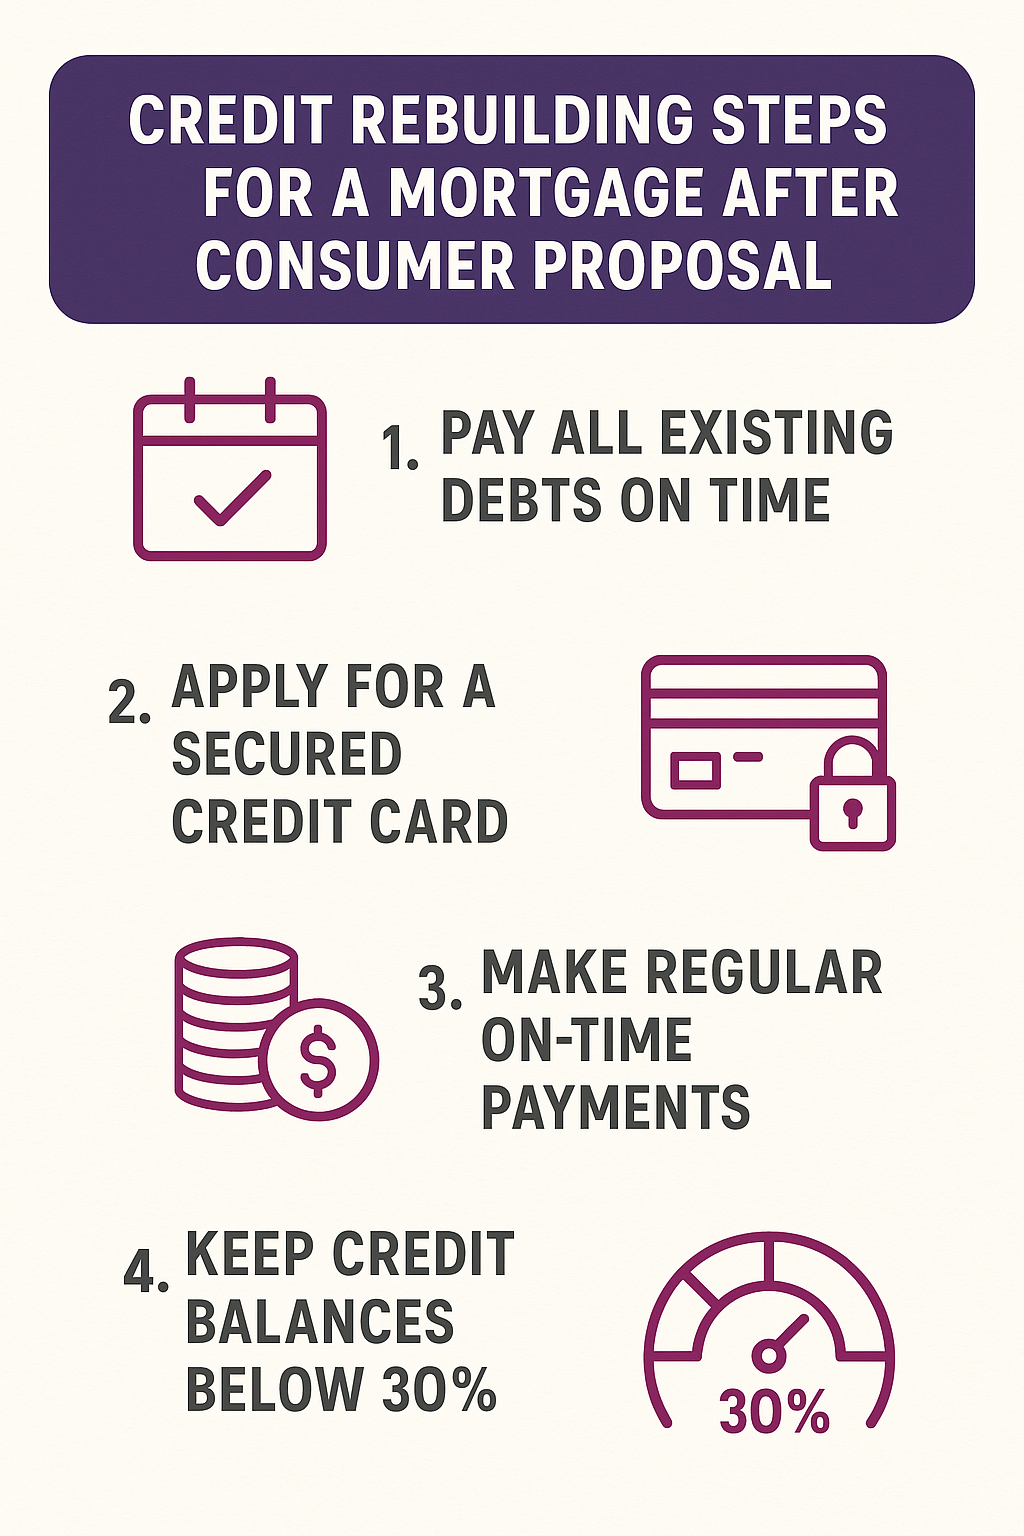
Open a secured credit card soon after filing, use it for small purchases, and pay it in full every month. After 6 to 12 months, you can often move to an unsecured card. Lenders like to see one or two active accounts with 12 or more months of on-time payments. Keep balances below 30% of your limits.
Common mistake: avoiding all credit after a proposal. No credit history means no proof of recovery, and that delays approval.
2. Make Every Payment on Time
Your report should tell a simple story: you borrowed and you paid on time. Set up automatic payments for your proposal, your new credit and your bills.
3. Build Your Down Payment or Equity
More money down means less risk for the lender. For purchases, aim for at least 20%. For refinances, keep your loan-to-value conservative.
4. Lower Your Debt Ratios
Lenders limit how much of your income can go to housing and debt. Avoid new car loans or financing before you apply, and pay off small balances.
5. Document Stable Income
Stay with your employer for at least 12 months if you can. If you’re self-employed, file your taxes on time and show enough income to support the payment.
6. Add a Co-Signer or Guarantor
A family member or partner with strong credit and income can help you qualify sooner. They’ll share responsibility for the mortgage, so make sure everyone understands the commitment.
7. Work With a Broker Who Knows Proposal Files
A broker who handles consumer proposal files knows which lenders approve during a proposal, which need the Certificate of Full Performance, and which accept gifted down payments. They also present your story to underwriters in the best light. Using one broker avoids multiple credit checks from scattered applications.
Buying vs Refinancing After a Consumer Proposal
Buying a home
- A bigger down payment offsets recent proposal history.
- Expect the lender to review your file by hand. Be ready to explain what caused the proposal and what has changed.
- A co-signer can help, but the payment still needs to be affordable long term.
Refinancing your current home
- Equity-based approvals are common with private and B lenders.
- A refinance can pay out your proposal and start your recovery sooner.
- Compare fees and any prepayment penalty against the savings over the next 12 to 36 months.
Common Mistakes to Avoid
- Applying too early, with no new credit or recent late payments
- Running up new credit cards to high balances
- Taking a car loan before your mortgage
- Missing documents, such as no paper trail for your down payment or missing Notices of Assessment
- Applying at several lenders yourself and triggering multiple credit checks
Consumer Proposal Mortgage Options at a Glance
| Stage | Typical lender | Down payment or equity | What matters most |
|---|---|---|---|
| Active proposal | Private, select B lenders | 20% or more equity; 20% to 35% down to buy | Equity and exit plan |
| 0 to 12 months after completion | B lenders, some private | 20% or more | Certificate of Full Performance, new credit |
| 12 to 24 months after completion | B lenders | 20% or more | Clean credit history, stable income |
| About 24 months and beyond | Banks, insured mortgages | From 5% insured | Rebuilt credit and standard qualifying |
General guide only. Every lender sets its own rules, and approval depends on your full application.
You Are More Than Your Credit Score
A consumer proposal is a legal tool designed to help people recover from serious debt. Using it isn’t a failure. It’s a decision to take responsibility and move forward with a plan. Your credit score measures one part of your finances at one point in time, not your worth or your future.
How LendToday helps: our team has more than 30 years of combined experience helping Canadians buy, refinance and renew during and after consumer proposals. Led by David Cumberbatch and David Jeffrey, we work with private, B and bank lenders at every stage of credit recovery. We give every file the same care and discretion, and a clear plan from where you are today to the lowest rate you can qualify for.
FAQs: Mortgages After a Consumer Proposal
1. Can I get a mortgage while I’m still in a consumer proposal?
Yes, mainly through private and select B lenders. Approval depends on your equity or down payment and your ability to make the payment. Most banks decline during an active proposal.
2. How long after a consumer proposal can I get a mortgage from a bank?
Usually about two years after completion, with rebuilt credit and stable income. B lenders can often approve you within the first year after completion.
3. Can I use a second mortgage to pay off my consumer proposal?
Yes, if you have enough equity. A private second mortgage or refinance can pay the proposal in full, and you can usually pay a proposal off early without penalty. Finishing early starts your credit recovery sooner.
4. Can you get a mortgage with an R7 credit rating?
Yes, through private and some B lenders that focus on equity and income. Banks generally wait until the proposal is complete and your credit has recovered.
5. What is a Certificate of Full Performance?
It’s the document your Licensed Insolvency Trustee issues when you’ve completed your proposal. Lenders require it for any post-proposal mortgage, so ask for it as soon as you finish.
6. How much down payment do I need after a consumer proposal?
B lenders typically want at least 20%. During an active proposal, expect 20% to 35% to buy. About two years after completion, insured mortgages with smaller down payments may be possible.
7. Can a co-signer help me get a mortgage after a consumer proposal?
Yes. A co-signer with strong credit and income can improve your approval odds, but they share responsibility for the mortgage.
8. Will my mortgage rate be higher after a consumer proposal?
At first, usually yes. As your credit recovers, you can often refinance into a lower rate, which is why a staged plan matters.
Next Steps
Whether you’re in a consumer proposal, recently finished, or planning ahead, the right plan gets you approved sooner and lowers your cost over time:
- Rebuild credit: one or two new accounts, low balances, automatic payments.
- Get your documents ready: proposal documents, income, and down payment history.
- Choose your lender path: the fastest approval now, with a plan to move to a lower rate later.
- Set milestones: know when you’ll be ready for each step.
Learn more about consumer proposals and bankruptcy or how debt consolidation compares to a consumer proposal.
Rates are estimates only, subject to change and lender approval.