Table of Contents
ToggleYour Home May Be Worth More to You Than You Think
Most Ontario homeowners know roughly what their house is worth. Far fewer know how much of that value they can actually use.
That gap matters. Home equity can consolidate high-interest debt, fund a renovation, cover a spousal buyout, help a child with a down payment, or bridge you through a tough stretch. Yet many homeowners assume the door is closed because their bank said no, their credit took a hit, or they simply never ran the numbers.
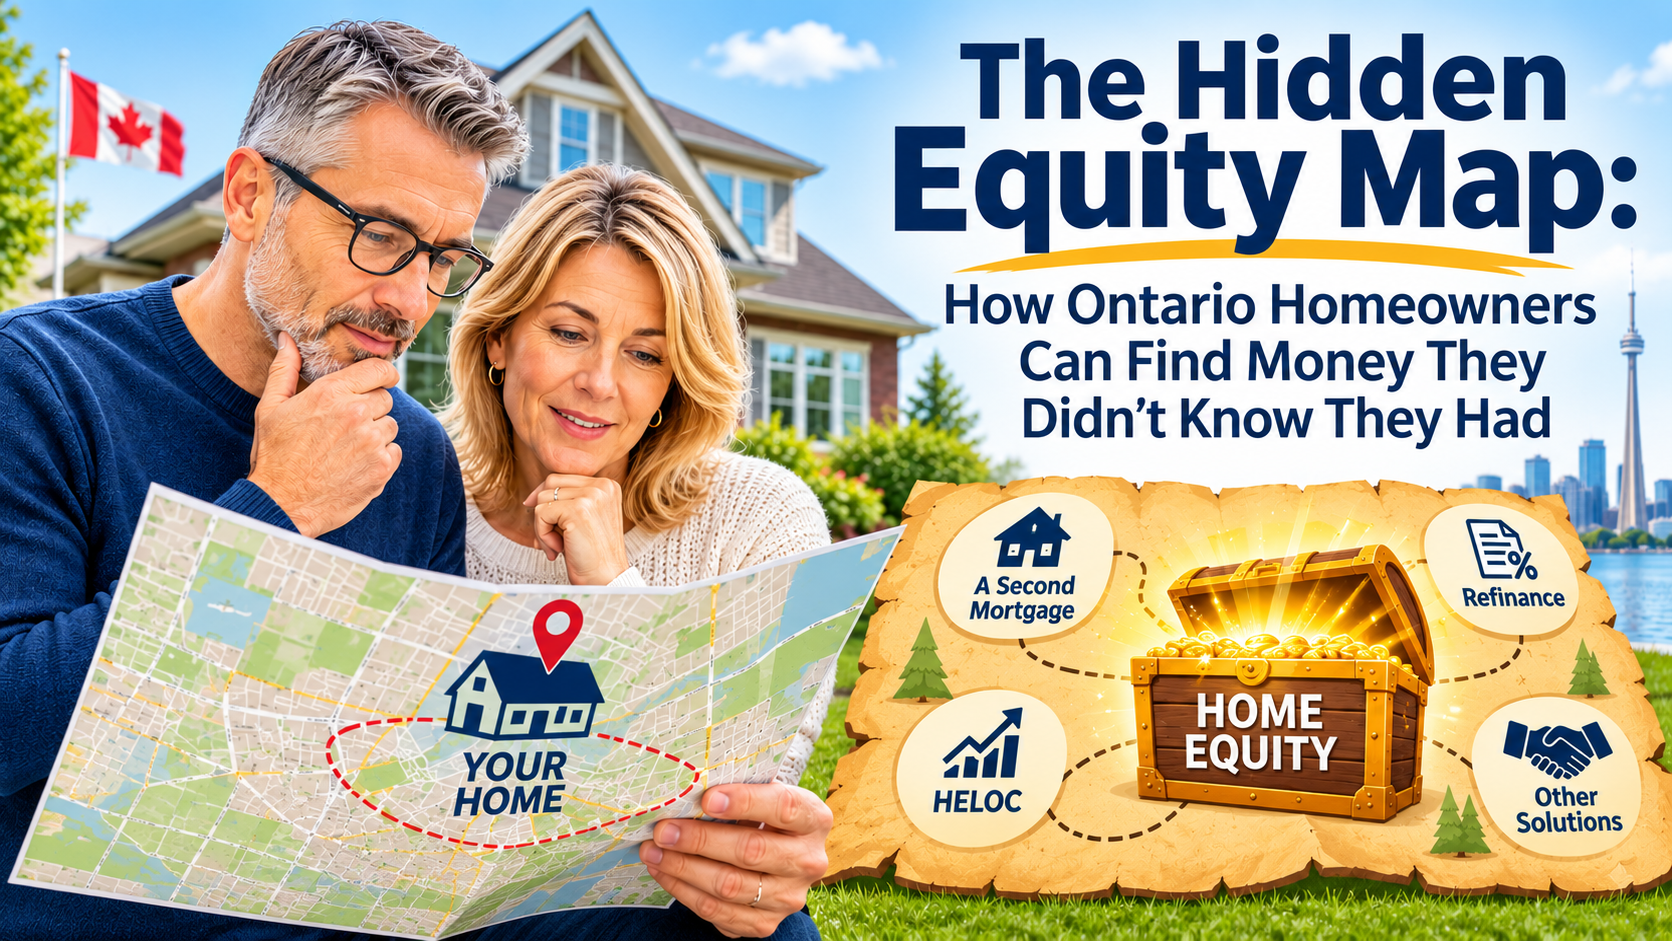
This guide is your equity map. We’ll show you how to calculate your equity, where hidden equity comes from, what quietly shrinks it, and how banks, B lenders, and private lenders each look at the exact same home very differently.
At LendToday, with access to over 50 lenders, we help homeowners find and unlock equity every day. Often, the money is already there. It just needs the right lender.
What Home Equity Is and How to Calculate It
Home equity is the part of your home you own outright. In its simplest form:
Home equity = current market value minus everything registered against the property
If your home is worth $800,000 and you owe $420,000 on your mortgage, your total equity is $380,000.
But lenders never lend against all of it. They use a measure called loan-to-value (LTV), which compares the total amount borrowed against the home to its appraised value. Each lender sets a maximum LTV, and that limit decides your usable equity:
Usable equity = (home value × maximum LTV) minus existing debts on the property
Using the same example with an 80% LTV limit: $800,000 × 80% = $640,000. Subtract the $420,000 mortgage and you have about $220,000 in usable equity.
That’s the number that actually matters, and it can change dramatically depending on which lender you work with.
Where Hidden Equity Comes From
Equity builds quietly in the background. Here are the most common sources homeowners overlook.
Market appreciation since you bought. If you purchased in Durham Region or the GTA more than five years ago, your home has likely gained substantial value even after recent market cooling. Many owners still picture their purchase price instead of today’s value.
Years of principal paydown. Every regular payment chips away at your balance. After 8 to 10 years of payments, the reduction can be significant, especially on a shorter amortization.
Renovations and upgrades. A finished basement, new kitchen, updated bathrooms, or an added legal secondary unit can raise appraised value well beyond what you spent.
A paid-off or nearly paid-off home. Retirees and longtime owners often hold most of their net worth in their homes but have never borrowed against them.
Land and lot value. Larger lots, corner lots, and properties with severance or development potential can carry value that a quick online estimate misses.
Rental and secondary properties. A cottage, rental unit, or investment property may hold equity you can tap without touching your primary residence.
What Quietly Shrinks Your Usable Equity
Some things reduce the equity a lender will actually count, even when your home’s value looks strong on paper.
- Secured lines of credit. Lenders count the full registered limit of a HELOC, not just what you’ve drawn. A $100,000 limit with a $10,000 balance can still use up $100,000 of room.
- Collateral charges. Some bank mortgages are registered for up to 125% of the home’s value. This can make refinancing elsewhere more complicated.
- Liens and judgments. CRA liens, construction liens, and court judgments registered on title must usually be paid out before or during any new financing.
- Property tax arrears. Unpaid municipal taxes rank ahead of https://www.equifax.ca/personal/ most mortgages, so lenders deduct them first.
- Condition and location issues. Deferred maintenance, rural locations, unusual properties, and unpermitted renovations can lower the appraised value or the LTV a lender will offer.
- A falling local market. If values in your area have softened, your equity may be lower than it was a year or two ago.
The good news: most of these can be planned around. A broker can review your title, identify what’s registered, and structure the financing so these issues are cleared as part of the deal.
One Home, Three Very Different Answers
Here’s where the equity map gets interesting. Banks, B lenders, and private lenders each look at your home through a different lens, so the same property can produce very different results.
Banks (A lenders) offer the best rates but focus heavily on your income, credit score, and debt ratios. You must also pass the federal stress test. Strong equity alone won’t get you approved.
B lenders (alternative lenders and many trust companies) are more flexible on credit, self employed income, and past financial setbacks. Rates are higher than a bank’s but well below private rates.
Private lenders focus mainly on the property and your equity. They can fund quickly and work with credit issues, consumer proposals, and income that’s hard to document, at a higher cost and for a shorter term.
Let’s apply this to a sample Ontario home worth $800,000 with a $420,000 first mortgage. LTV limits shown are typical maximums; actual limits vary by lender, location, and file.
| Lender type | Typical max LTV | Max total borrowing | Usable equity | What it takes |
|---|---|---|---|---|
| Bank refinance | 80% | $640,000 | $220,000 | Strong credit, provable income, passing the stress test |
| B lender | Up to 80% | $640,000 | $220,000 | Fair credit, two years of income history, reasonable debt ratios |
| Private lender (urban) | About 75% | $600,000 | $180,000 | Solid equity and a clear exit plan |
| Private lender (rural) | About 65% | $520,000 | $100,000 | Solid equity, with lower limits for location |
Notice the twist. The bank offers the most usable equity, but only if you qualify. For a homeowner with bruised credit or self employed income, the bank’s answer is effectively $0, while a B lender or private lender can unlock six figures.
That’s why your usable equity isn’t one number. It’s a range, and the right lender decides where you land in it.
Smart Ways to Access Your Equity
Once you know what’s available, the next step is choosing how to unlock it.
Refinance your first mortgage. Replace your current mortgage with a larger one and take the difference in cash. Best when your rate is close to market and any prepayment penalty is manageable.
Home equity line of credit (HELOC). A revolving line you draw from as needed, paying interest only on what you use. Ideal for ongoing projects, but usually requires bank level qualification.
Second mortgage. Keep your existing first mortgage and add a second one behind it. Useful when breaking your first mortgage would trigger a large penalty or when you have a great rate you don’t want to lose.
Reverse mortgage. Available to homeowners 55 and older, with no regular payments required. Interest compounds over time, so it suits long term needs more than short term ones.
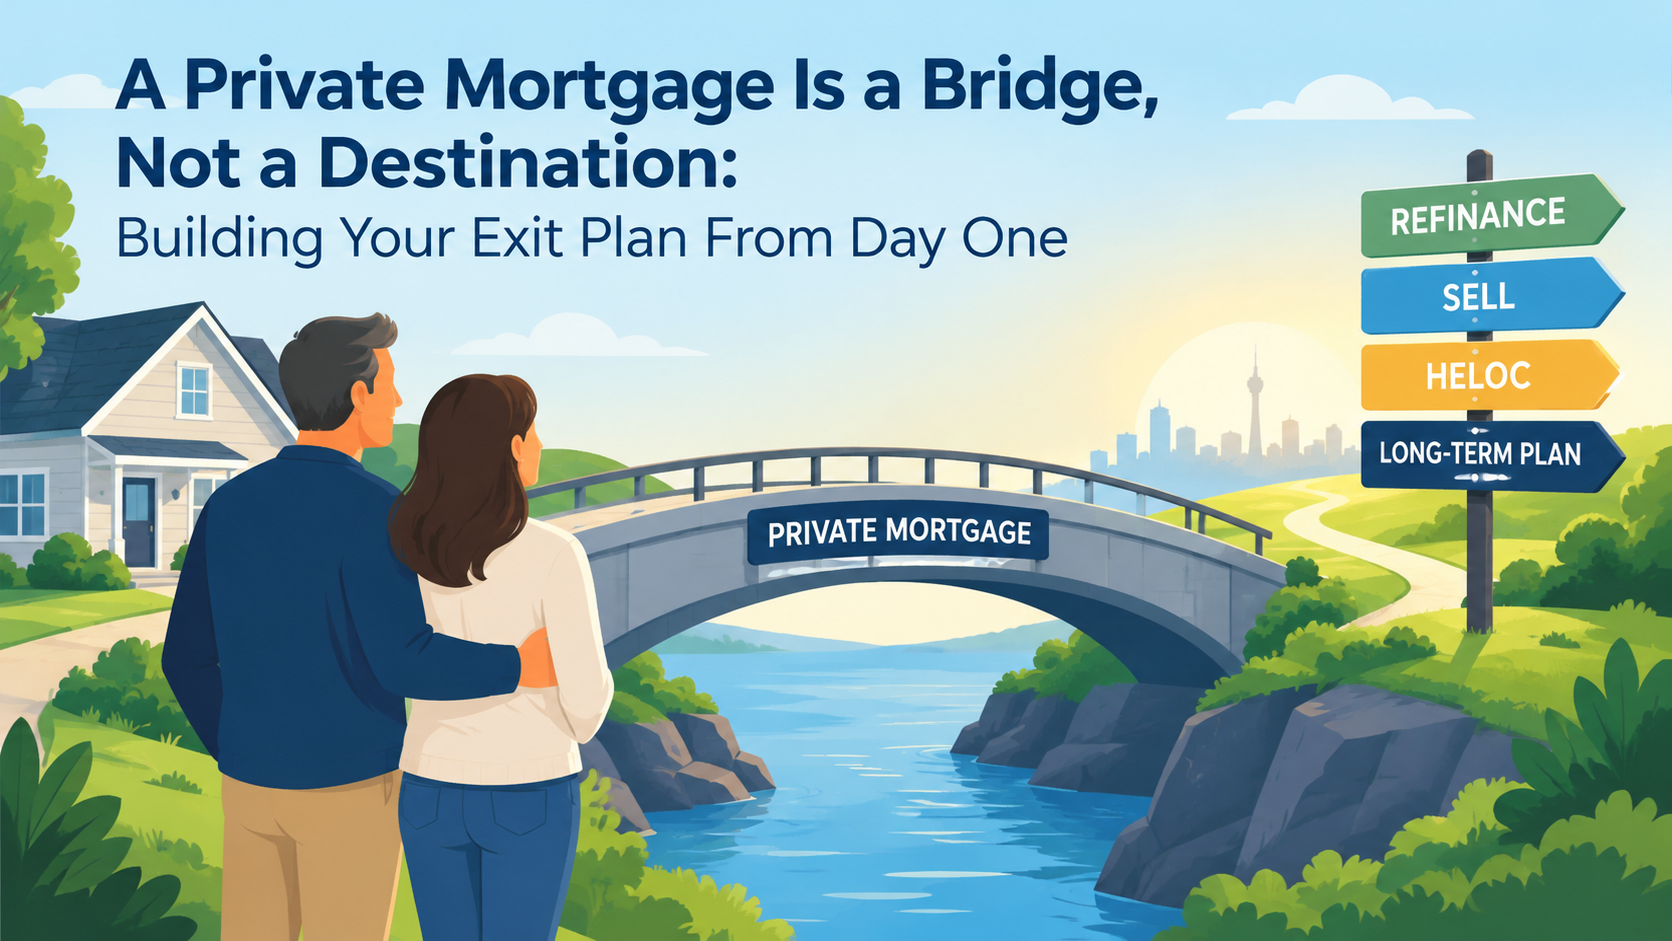
Private mortgage as a bridge. When timing, credit, or income documentation stands in the way, a short term private mortgage can unlock equity now, with a planned move back to a bank or B lender later.
The right choice depends on how much you need, how long you need it, what it costs to break your current mortgage, and how you’ll pay it back.
Let LendToday Map Your Equity
A bank can only tell you what that one bank will do. A broker can show you the whole map.
At LendToday, we review your home’s value, your title, and your full financial picture, then match you with the lender that unlocks the most equity at the lowest cost.
- Over 50 lenders in one place. Banks, credit unions, B lenders, and private lenders, so you see every option side by side.
- A full title and equity review. We spot HELOC limits, collateral charges, liens, and tax arrears before they become surprises.
- Options for bruised credit and self employed income. A bank decline doesn’t mean your equity is out of reach.
- A plan for today and tomorrow. If private or B lending is the right first step, we build the route back to better rates from day one.
As a licensed Ontario mortgage brokerage (FSRA #13691) based in Oshawa, we help homeowners across the province turn equity into real solutions.
Curious how much equity you can unlock? Try our free Equity Check tool for a quick estimate, or call us at 1-855-242-7732 to talk with our team.
Frequently Asked Questions
How much equity can I borrow against my home in Ontario?
Most lenders allow total borrowing of up to 80% of your home’s appraised value on a refinance. Private lenders often lend up to about 75% in urban areas and less in rural ones.
How do I calculate my home equity?
Subtract everything registered against your property from its current market value. To find usable equity, multiply your home’s value by the lender’s maximum loan to value, then subtract your existing debts.
Can I access home equity with bad credit?
Yes. B lenders and private lenders focus more on your equity and property than on your credit score. Rates are higher, so it’s smart to plan a move back to a bank once your credit improves.
Does a HELOC reduce my available equity?
Yes. Lenders count the full registered limit of a HELOC, not just your balance. Lowering or closing an unused limit can free up borrowing room.
Is it better to refinance or get a second mortgage?
It depends on your current rate and prepayment penalty. If breaking your first mortgage is expensive, a second mortgage may cost less overall. A broker can compare both side by side.
Do I need an appraisal to access my equity?
In most cases, yes. Lenders use a professional appraisal to confirm your home’s value before approving any equity based financing.